
Cryptocurrency Patent Examples from Top Companies
Cryptocurrency was first invented in 2008 with the release of Bitcoin, the first public digital currency characterized by decentralized control, user anonymity, and…
The Financial Technology industry, commonly referred to as “FinTech,” is a developing industry that leverages digital technology to increase efficiencies in banking, financial services, and payment systems in fields including digital assets, distributed ledgers, digital marketplace financing, investment advice, etc. But what intellectual property protections are available to prevent someone from stealing your technology? In this article we discuss everything you need to know about patents for FinTech software, and the other IP that completes a FinTech strategy.
It’s hard to deny the innovation boom in the FinTech sector. Global FinTech investment reached $103.1 billion across about 2,100 deals in the first half of 2026, according to KPMG’s Pulse of Fintech. Many banks and FinTech startups are racing to build their patent portfolios by acquiring disruptive technology in blockchain and payment companies as financial institutions and banks are quickly understanding the role of intellectual property in their business and monetization strategies. A 2019 study of FinTech patenting found that electronic and mobile payments drove the biggest surge in filings.
However, the rise of cryptocurrency and blockchain patents has enabled the emergence of many new FinTech startups and global FinTech hubs. Many of the startups are leveraging business and competitive intelligence to develop patent portfolios around FinTech trading in stocks and commodities, mining of cryptocurrencies, and block chain implemented financial security protocols which address the complex financial regulatory environment.
The technological advantages in the FinTech sectors aimed at developing better customer-centric technology and intuitive product designs not only help prevent customers from switching to a competitor, but may be implemented in other industry sectors such as healthcare, aerospace, and automotive manufacturing. However, without the right protections directed toward your software implemented technology or business method, you may become the victim of the “second mover advantage”—a term used when a company comes after the pioneer in the industry and utilizes the pioneer’s proprietary technology to build a superior product and capture a greater percentage of market share.
For example, after PayPal was created to simplify online payments, competitors such as Apple Pay, Google Wallet, Stripe, and Square developed their own, highly-successful and widely-used online merchant payment systems.
A patent is a grant from the U.S. Patent and Trademark Office that lets its owner exclude others from making, using, selling, offering to sell, or importing the claimed invention for a limited time. It contains a technical description with drawings and one or more claims that set the metes and bounds of the protection.
As explained in our Can You Patent An Algorithm article, 35 U.S.C. 101 allows patents on processes, machines, manufactures, and compositions of matter. FinTech patents usually claim processes or systems in banking, investing (such as robo-advisors), payments, blockchain and cryptocurrency, financial security, and lending.
Software patents cover the methods and systems the code implements, not the code itself, which is protected by copyright.
Patents tell investors and buyers whether a FinTech company’s innovations are proprietary or up for grabs. The right to exclude others creates a competitive advantage, and that advantage supports a higher valuation. Large institutions use intellectual property to block newcomers, and startups rely on disruptive innovations to win market share.
The innovation and technology that drives most FinTech patents are often associated with computer-implemented inventions and business methods where the sour taste of the 2014 Supreme Court decision in Alice Corp. v. CLS Bank International has left many still wondering what is considered “abstract” when drafting software claims.
First, understand the inventive concept in your invention and be able to articulate how the claimed invention provides a technical solution to a technical problem. Include specific features that were specifically designed to achieve an improved technological result or improvements to a technical field.
Second, understand if your software improves a way that a computer functions or employs any new functionality to improve the user experience over traditional methods or technology. Clearly describe any system, sub-systems, or components used to execute your novel process or method.
Avoid the discussion of generic computer components, or fundamental economic principles, or methods such as risk mitigation or hedging that may be construed as merely “organizing human activity” or as reciting “conventional actions in a generic way.” Lastly, avoid simply focusing on data storage and aggregation, or merely organizing information that may be performed on a conventional or generic computer.
Yes, but only if the claims pass the Section 101 eligibility test. In Bilski v. Kappos (2010), the Supreme Court held that business methods are not automatically excluded from patent protection, but it rejected a claim to hedging risk in commodity trading as an abstract idea. In Alice (2014), it held that running an abstract financial idea on a generic computer does not make it eligible.
So a financial product is not patentable as such, but a specific technical way of delivering it can be, such as a new fraud detection architecture or a more secure payment protocol. The USPTO’s eligibility guidance is in MPEP 2106 and was updated in 2025 and 2026, including the precedential Ex parte Desjardins decision, which treats an improvement to how a machine learning model works as a technical improvement.
[RLG]Free strategy call
Talk it through with a registered patent attorney.
Free 15 to 45 minute IP strategy call, no obligation.
A non-provisional patent application is a type of application that protects novel, non-obvious, and useful products, processes, machines, and devices and provides 20 years of protection from your filing date. Before filing your FinTech application, it’s recommended you conduct a Prior Art Search to determine the patentability of your invention and help identify all “novel” features and functionality that will be the scope of your claims. If patentable, ensure that you have clearly identified the “point of novelty” in your invention and only file when you have a finalized invention. Ensure all features and functionality from your Beta test have been captured and articulated in the claims or detailed description.
For those FinTech companies who are still developing and finalizing their inventions, it is recommended that you start with a provisional patent application which provides 12 months of “protection” while you continue to develop and Beta test your software. When your development is finalized, file a non-provisional patent application within those 12 months and claim priority to your provisional patent application filing date.
A Graphical User Interface (GUI) may be patentable as a design. To meet the “article of manufacture” requirement, the GUI must be shown embodied in a display screen or panel (or a portion of one), such as on a computer, tablet, or mobile device. Your GUI design patent application may include multiple embodiments as long as those embodiments relate to a single design. The display is usually drawn in broken lines so that only the interface is claimed, and a broken line statement is essential to explaining what portions of the GUI are claimed.
A design patent protects the ornamental and non-functional appearance of your invention for a term of 15 years from the issue date (for applications filed on or after May 13, 2015). Design patents for GUIs are advantageous as compared to non-provisional utility patents for a number of reasons including a faster prosecution (first action pendency for design applications was 14 months in May 2026) and relatively inexpensive costs. This cost-effective strategy allows FinTech companies to protect a variety of GUIs for a fraction of the cost of a non-provisional utility application.
Patent prosecution is the back-and-forth with the USPTO examiner, from filing through office actions and your responses, until the application is allowed or finally rejected. The US patent office (USPTO) has worked diligently to reduce patent examination timelines. However, average first action pendency (i.e., the period between filing your application and receiving a “first action” from the USPTO) for a non-provisional patent application was about 20.5 months in fiscal year 2026 and, in many cases, takes much longer with software applications. One of the most overlooked programs offered at the USPTO is “Track One” Prioritized Examination.
Track One Prioritized Examination is a “request” filed with your Non-Provisional Patent Application to expedite your application with the goal of obtaining a final disposition within about 12 months. The USPTO accepts up to 20,000 requests per fiscal year, limits the application to four independent claims and 30 total claims, and charges an additional fee of $4,515 (large entity), $1,806 (small entity) or $903 (micro entity). In return, Track One can greatly reduce your prosecution time.
A FinTech IP strategy decides what to patent, what to keep secret, how to protect the brand, and how to grow a portfolio. Before filing, ask:
What’s in it for you? Does a patent give you a competitive advantage, by protecting the technology you use or covering alternatives competitors might adopt?
Am I covered? One patent is rarely enough for one product. Portfolios grow around the core method, its improvements and alternatives. Set an IP budget and use invention disclosure forms so your team records new ideas.
Is everything in the application? If it is not in the application, it is not covered, and new matter cannot be added after filing. Some technology is better kept as a trade secret, despite the risk of independent development. Tell your attorney what you do not want published.
Once a FinTech patent issues, its owner can send cease and desist letters and sue infringers in federal court. A competitor infringes only if its product or process falls within at least one claim. Accused infringers often challenge validity, in court (often arguing the claims are abstract under Alice) or at the USPTO’s Patent Trial and Appeal Board through inter partes or post-grant review. The covered business method review program, widely used against financial patents, ended in September 2020.
Start with a prior art search. A patent built on incomplete information can be rejected, or struck down later by the Patent Trial and Appeal Board or a court, even after it is granted. Reviewing published patents shows what is already public so your claims focus on what is new, and competitors’ patents give you competitive intellectual property intelligence. Then decide what the key concept of your invention is, what a competitor would have to do to copy it, and what alternative solutions reach the same result, and make sure the claims cover them.
FinTech intellectual property combines patents with trade secrets, copyrights, trademarks, and contracts.
Trade secrets are the opposite of a patent: patents are published, trade secrets are not. Any information that is not publicly known and gives a competitive advantage can qualify, such as client lists, vendor lists, risk models, and business plans. Trade secrets can last indefinitely, but only with reasonable measures to keep them secret, such as non-disclosure agreements and limited access.
Copyrights protect the expression of ideas in tangible media. This can include code stored on a computer (including source code, object code, and pseudo code), graphical/visual interface features (similar to paintings and drawings), and text regarding your FinTech software (including user manuals and internal guides).
Trademarks are source indicators. A trademark distinguishes your brand and can be a word, phrase, slogan, logo, and even a sound or a smell. Marks can be registered federally with the USPTO and with the states.
Trademark infringement in FinTech usually involves a competitor using a confusingly similar name or logo for related financial services, such as a payment app, a crypto exchange, or a lending platform. The test is whether the use is likely to cause confusion about the source (15 U.S.C. 1114 and 1125). Clear a name before launch, because renaming a live financial product is costly.
Licensing lets you earn from FinTech IP without selling it, for example by licensing patented payment technology to banks or cross-licensing with a competitor. A license should set the field of use, territory, exclusivity, royalties, and who enforces the IP.
First, you have to own it. Make sure everyone who works for your business has agreed in a written contract to assign their intellectual property rights to the company. Code from an outside contractor is generally not a “work made for hire,” so without a written assignment the contractor may own the copyright.
They are separate systems. A patent or trademark does not let you offer a financial product, and a regulatory approval, such as a money transmitter license, does not protect your technology or brand. RegTech tools for compliance, identity checks, and fraud monitoring can be patented if they pass the same Section 101 test.
According to a 2019 patent trends study, the top FinTech patent holders in the U.S. were:
We’ve also put together an in-depth list of top companies in FinTech related patent filings and given you exclusive access!
Here are just a few examples of FinTech patents that have been granted:
Square (now Block) was granted a patent for a system allowing for real-time transfers between parties who are utilizing different assets (e.g. USD and cryptocurrency) while avoiding the volatility of exchange rates between fiat currencies and cryptocurrencies.
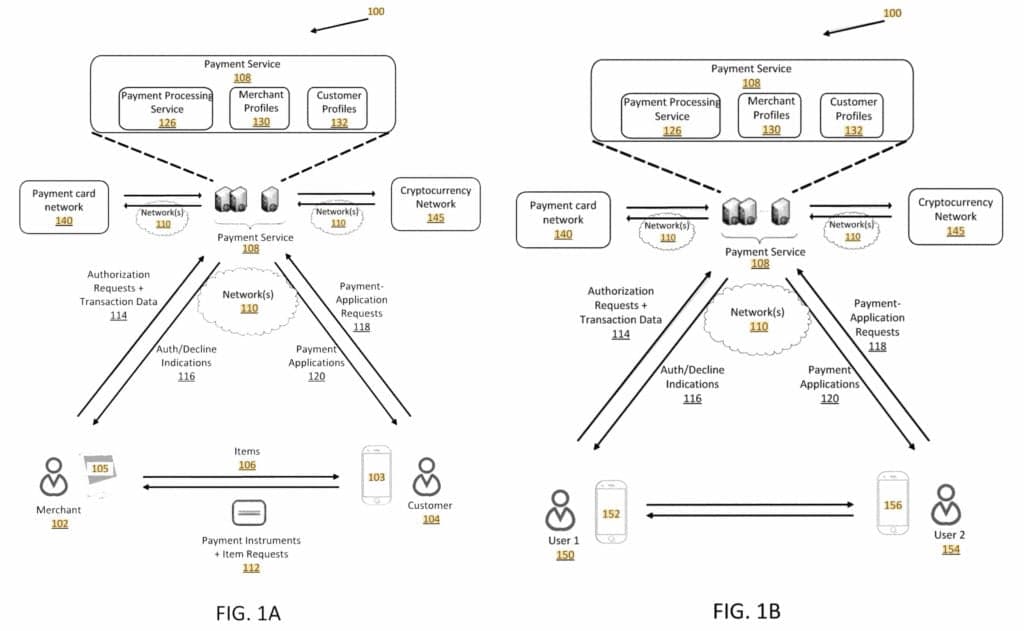
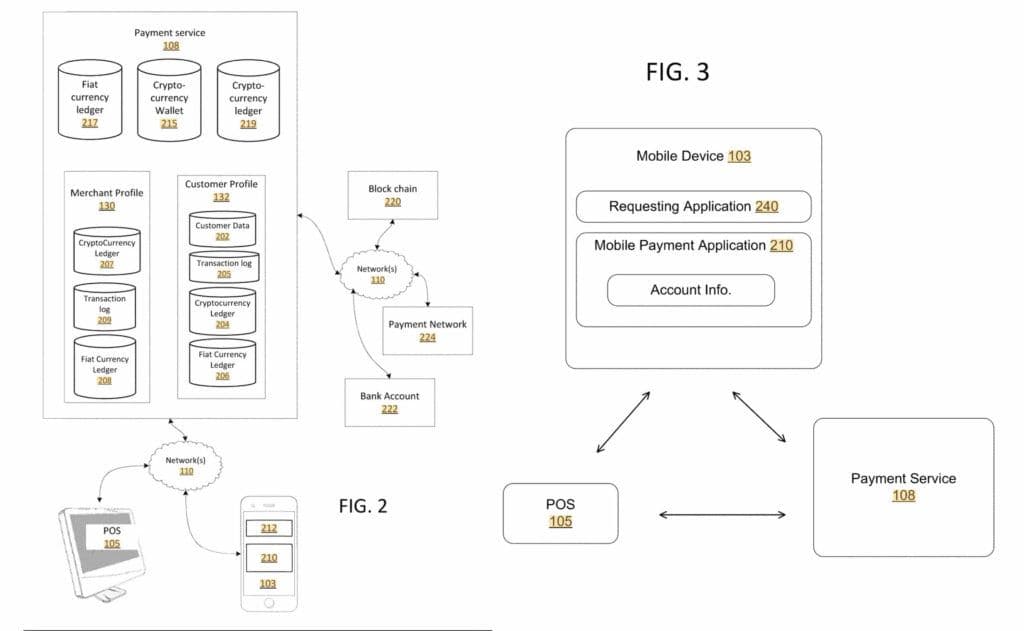
FIG. 2 illustrates and example payment service in accordance with some embodiments;
FIG. 3 illustrates and example mobile device and payment application in accordance with some embodiments;
Click here to see more info regarding this granted patent.
Bank of America was granted a patent for a multi-tiered digital currency wallet, which features multiple layers of access to assets. The wallet splits funds into a secured core and several password-protected tiers, so each password unlocks only its assigned share of funds.
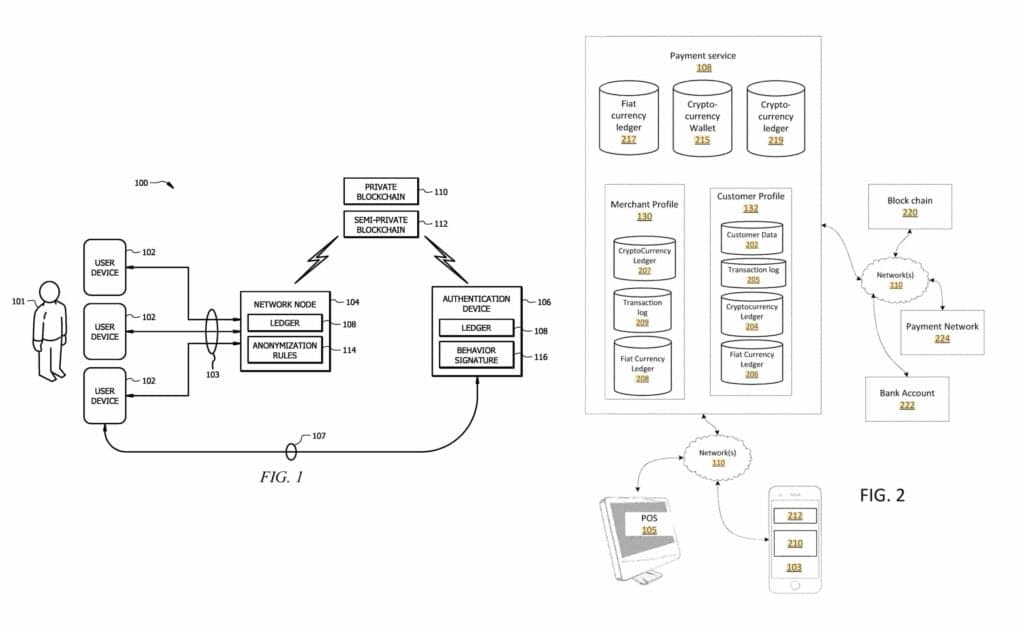
FIG. 1 is a schematic diagram of an embodiment of an information security system 100.
FIG. 2 is an illustrated example of a mapping between a private blockchain 110 and a semi-private blockchain 112.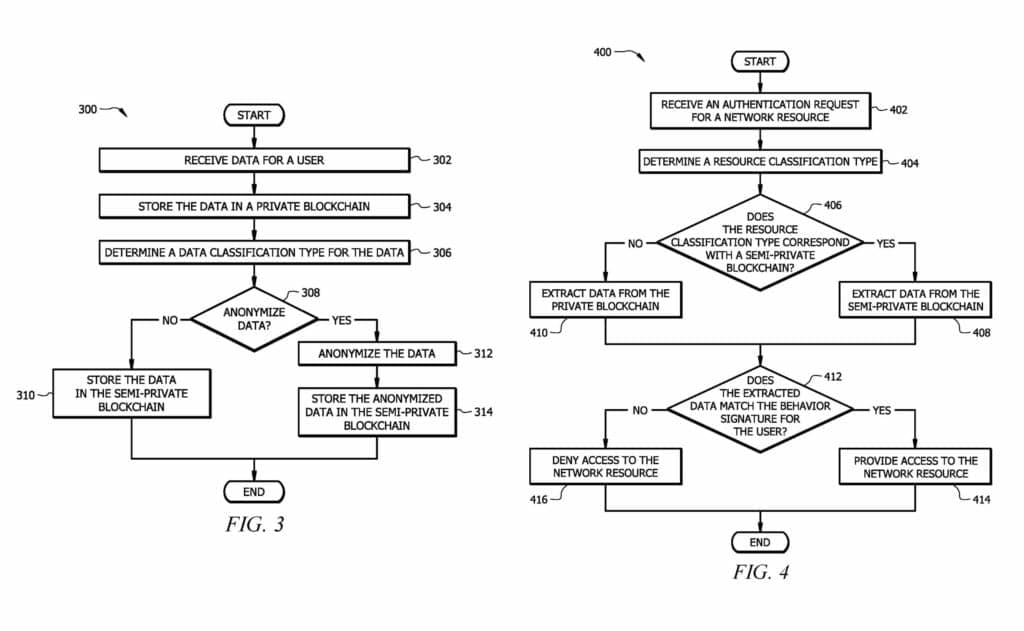
FIG. 3 is a flowchart of an embodiment of an information security method 300 implemented by the information security system 100.
FIG. 4 is a flowchart of an embodiment of an authentication method 400 implemented by the information security system 100.Click here to see more info regarding this granted patent.
Amazon was granted a patent for a non-contact biometric identification system that supports palm-print payments. An infrared scanner captures images of a shopper’s palm, and neural networks turn them into a signature that is matched against stored signatures, so shoppers can pay by holding a hand over the scanner instead of presenting a card.
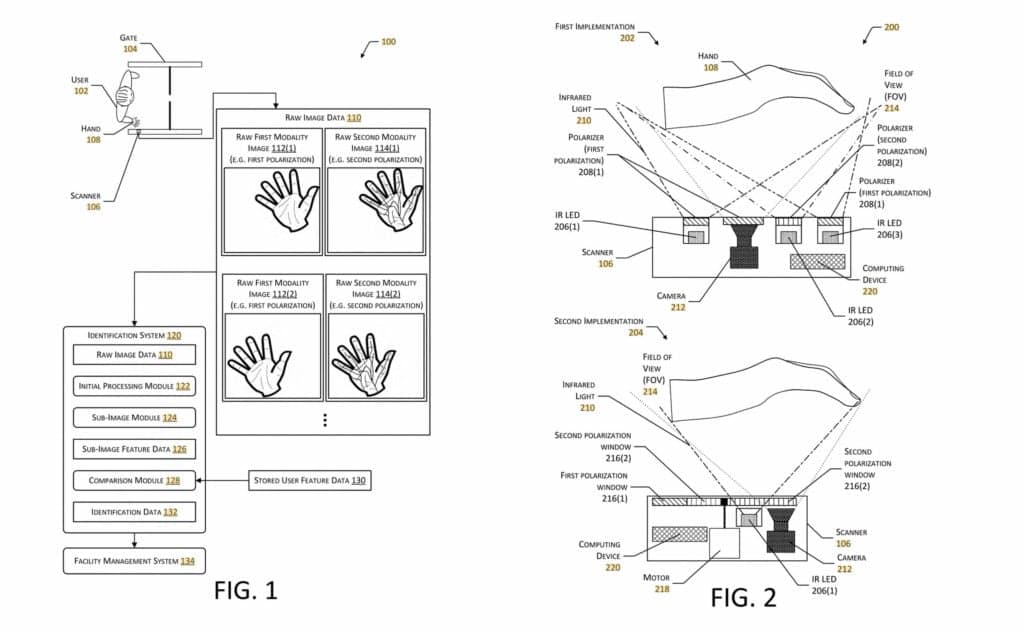
FIG. 1 illustrates a system to identify a user at a facility, according to some implementations.
FIG. 2 illustrates implementations of a scanner used to acquire raw image data of a user's hand, according to some implementations.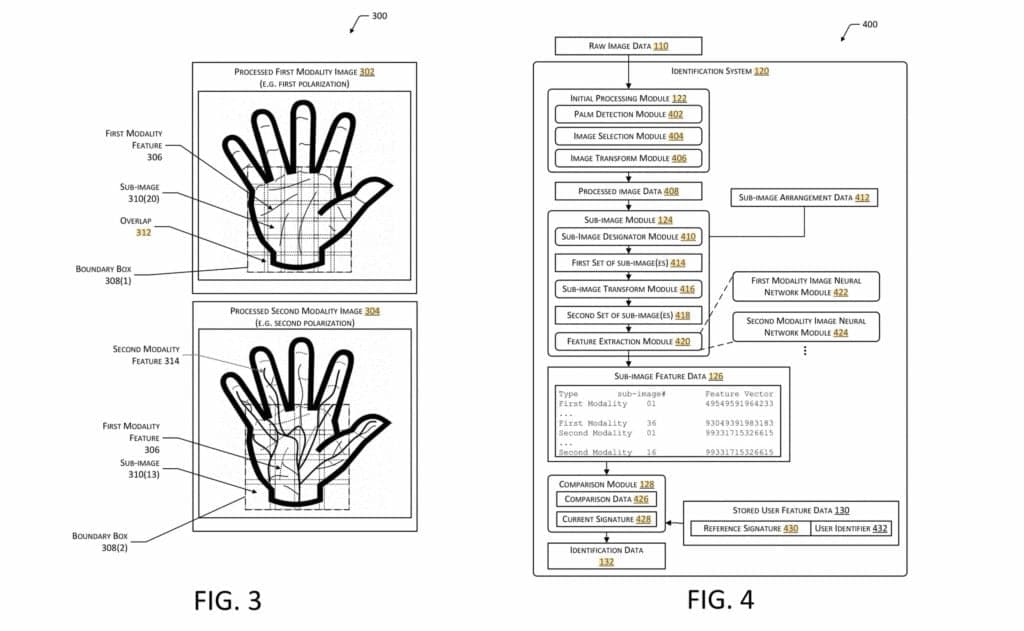
FIG. 3 illustrates a processed first modality image obtained using light with a first polarization and a processed second modality image obtained using light with a second polarization, according to some implementations.FIG. 4 is a block diagram of an identification system, according to some implementations.Click here to see more info regarding this granted patent.
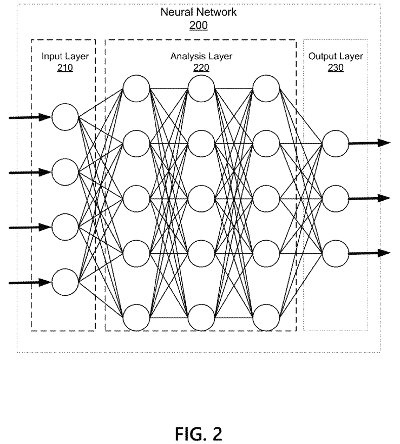
Capital One was granted a patent for technology that builds baseline and dysfunctional spending profiles for an account and checks each pending purchase. A purchase outside the baseline needs a second approval from a designated person. A neural network makes the decisions, which can help people with medical or memory conditions keep using a card more safely.
Click here to see more info regarding this granted patent.
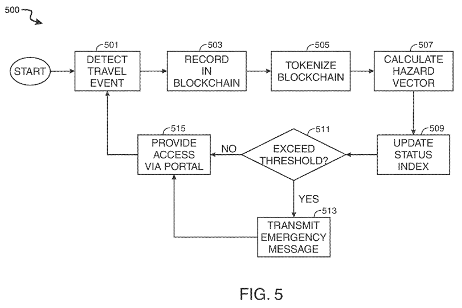
Bank of America was also granted a patent for a “digital passport with verified data provenance.” It records travel events in a blockchain ledger, tokenizes sensitive data, and calculates a hazard vector to flag trips above a set risk level, combining a security system with a digital wallet.
Click here to see more info regarding this granted patent.
A FinTech patent attorney is a lawyer registered to practice before the USPTO who understands software and financial services. FinTech IP counseling covers patentability searches, drafting and prosecution with Alice in mind, portfolio strategy, trademarks, license and assignment agreements, and enforcement.
The Rapacke Law Group is a fixed fee intellectual property law firm with a focus on software-implemented technologies including FinTech and SaaS. If you have questions on how best to protect your FinTech inventions, call for a free consultation or take our Intelligent IP Quiz to help you identify what type of protections are best for your business.
[RLG]Free strategy call
Talk it through with a registered patent attorney.
[01]Keep reading
Cryptocurrency was first invented in 2008 with the release of Bitcoin, the first public digital currency characterized by decentralized control, user anonymity, and…
Innovators worldwide filed a record 3.7 million patent applications in 2024, with U.S. patent activity surging in artificial intelligence and advanced manufacturing. Many of these applications involve new processes, not just products.
The list includes patents in the financial technology industry, including patents related to securities, business transactions, financial instruments, financial and…
The #1 top reviewed IP law firm.* Talk to a registered patent attorney, free.
*#1 top reviewed means the most public client reviews on Google, Trustpilot and Avvo of any US patent or trademark firm.