
How to Craft a Startup Advisor Agreement Like a Tech Unicorn
Learn how to draft a startup advisor agreement with the right equity, vesting, and IP terms. Use FAST benchmarks and Carta data. Book a free IP strategy call.
[ARTICLE]Startups
Angel investor agreements are the term sheet that sets an early-stage deal's economics and control terms, plus the definitive documents that make it binding, such as a share purchase agreement, a convertible note, or a SAFE (Simple Agreement for Future Equity). Together they decide who owns what, who gets paid first, and who has a say in your company long after the check clears. The checks are getting bigger. Carta's State of Pre-Seed, Q2 2026 reports that the average pre-seed instrument reached $276,000, up 27% year over year. This guide covers the key provisions angels expect, how much equity they typically take, and when to bring in a lawyer before you sign.
These documents craft a clear framework for the partnership between startups and angel investors by clarifying mutual expectations and obligations. Angel investments frequently take the form of priced equity, convertible notes or SAFEs, which gives you flexibility to fit your startup's current situation and future development.
These agreements contain critical provisions covering total invested funds, company valuation at the time of investment, and the resulting ownership percentages investors receive. They also typically contain terms about investor compensation that can be adapted to each party's conditions. Investor rewards should match the risks investors take and align with your corporate objectives.
A term sheet works almost like a statement of intent. It shows an angel investor's serious interest in funding a new venture. It lays down preliminary outlines that pave the way for more detailed discussions on the way to a comprehensive angel investor agreement. Most of a term sheet is non-binding. The definitive agreements are binding, and only the check deposited into the bank account signals a completed deal.
The move from term sheet to definitive documents is where you should bring in an angel investor agreement lawyer. Your lawyer drafts or reviews the definitive documents and negotiates liquidation preference and control terms. Your lawyer also handles securities-law compliance, such as accredited-investor checks and the Form D filing due within 15 days of the first sale in a Regulation D offering. For a broader view of the full document set, see our overview of fundraising agreements designed for success.
Every angel term sheet sorts into two groups. Economic terms decide who gets paid, and control terms decide who makes the calls. Know what each one costs you before you sign.
Economic terms
Control terms
The structure you pick sets terms that follow your company through every later round. Angel deals generally take one of three forms.
Priced equity round. The angel buys common or preferred shares at an agreed valuation. Preferred shares add economics such as a liquidation preference. This structure fits larger checks when you are ready to put a price on the company.
Convertible notes. A convertible note is a short-term loan that converts into equity at your next funding round. It accrues interest and carries a maturity date. If it has not converted by then, the investor can generally seek repayment or convert. A valuation cap limits the conversion price, and a discount rewards the angel for investing early. Notes fit when you want to delay valuation but your investor wants debt-like protection.
SAFEs. A Simple Agreement for Future Equity also defers valuation. According to Y Combinator, however, a SAFE has no interest or maturity date. Deferred-valuation instruments dominate early rounds. Carta counted more than 11,500 pre-seed SAFEs and notes in Q2 2026, with an average instrument size of $276,000. SAFEs fit fast, small raises where speed matters most.
An angel term sheet is usually lighter than a venture capital term sheet. Expect fewer control provisions and more focus on price, conversion and payout.
Your equity stake is the percentage of the company an angel owns once the deal closes or the instrument converts. It comes from a simple formula, so you can calculate it before negotiations start.
No fixed percentage applies to every deal. Ownership comes from one formula. Divide the investment by the post-money valuation, or by the post-money valuation cap if you use a SAFE. Y Combinator's Post-Money SAFE User Guide shows how the numbers move at a $6.7 million post-money cap. Raising $500,000 sells roughly 7.5% of the company. Raising $1 million sells about 15%. These are worked illustrations, not market averages.
Here is a single-angel example. An investor writes a $100,000 check at a $5 million post-money cap. Dividing $100,000 by $5,000,000 gives 2% ownership, assuming the SAFE converts at the cap.
That 2% is measured before your next priced round. According to Y Combinator, new money and any option-pool increase in that round will dilute it. Model those future rounds before you sign.
A term sheet is the blueprint for your angel deal. It summarizes the economic and control terms you and your investor agree on before anyone pays for full drafting. A letter of intent plays a similar role, but it is a looser statement of interest that shows up more often in acquisitions than in equity financings. Most of a term sheet is non-binding, so either side can still walk away. Two clauses usually are binding. Confidentiality keeps the terms private. Exclusivity, often called a "no-shop," bars you from shopping the deal to other investors for a set period. Read both carefully before you sign.
A solid term sheet for an angel investment covers these terms, in this order:
Once the term sheet is signed, due diligence begins. Your counsel then converts it into the definitive agreements, such as the stock purchase agreement and investor rights agreement. Our Fundraising Agreements page explains how each document fits together.
An exit is the event that turns an angel's paper ownership into cash, and for most startups that event is an acquisition. Your agreement decides how the proceeds get split, so settle exit terms before you sign.
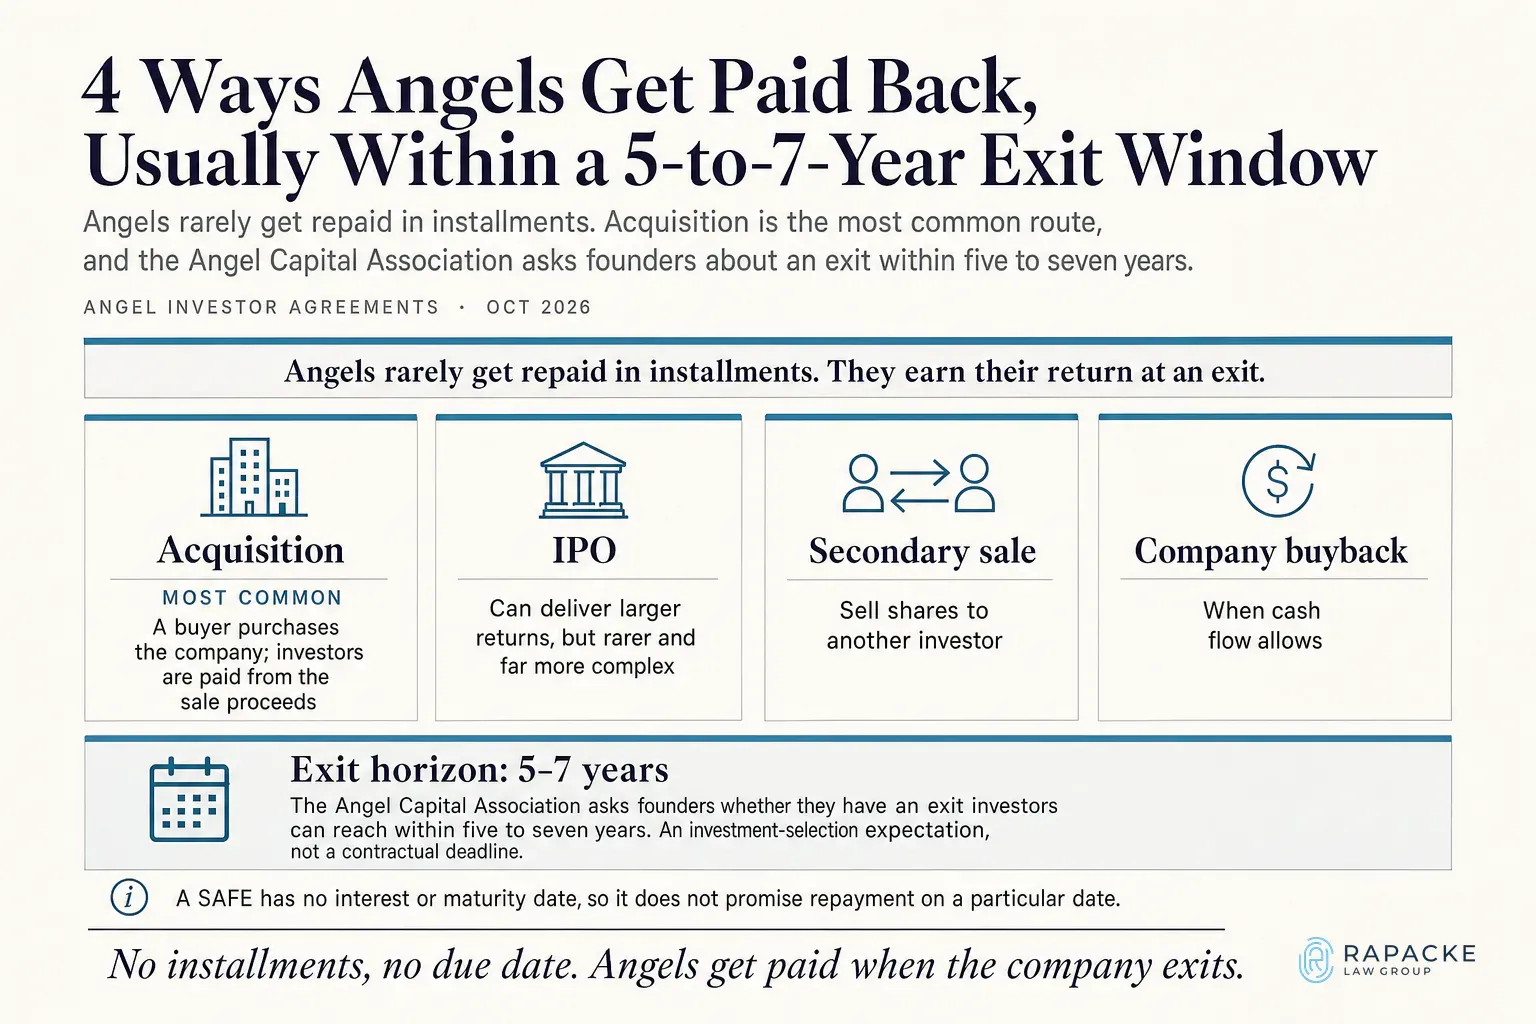
Angels rarely get repaid in installments. They earn their return at an exit. The most common route is an acquisition, where a buyer purchases the company and investors are paid from the sale proceeds. An IPO can deliver larger returns, but it is rarer and far more complex. Angels can also cash out through a secondary sale to another investor, or through a company buyback when cash flow allows. The Angel Capital Association encourages founders to ask themselves whether they have an exit strategy investors can reach within five to seven years, so expect that question.
Your agreement decides who gets paid and how. A liquidation preference lets preferred holders recover their investment before common shareholders. Drag-along rights let a majority force minority holders into an approved sale. Tag-along rights let minority investors join a sale on the same terms. For a deeper look, read our guide Exit Strategies for Angel Investors, How IP Drives Real Returns.
Most angel investor agreements settle four questions about control and visibility. The first is governance. Decide whether an angel gets a voting board seat or a non-voting observer seat, and put that choice in writing. The Angel Capital Association asks founders to consider whether they will accept board decisions they may not always agree with, so treat any seat as real authority. The second is information rights. Specify which financial records investors may inspect, which reports they receive, and how often those reports arrive. The third is pro rata participation, which is the right to invest in later rounds and protect ownership. Y Combinator moved this right out of its standard SAFE and into an optional side letter in 2018, so confirm whether your deal includes one. The fourth covers obligations on both sides. Founders deliver those reports on schedule and keep investors informed of major decisions. Investors keep company information confidential.
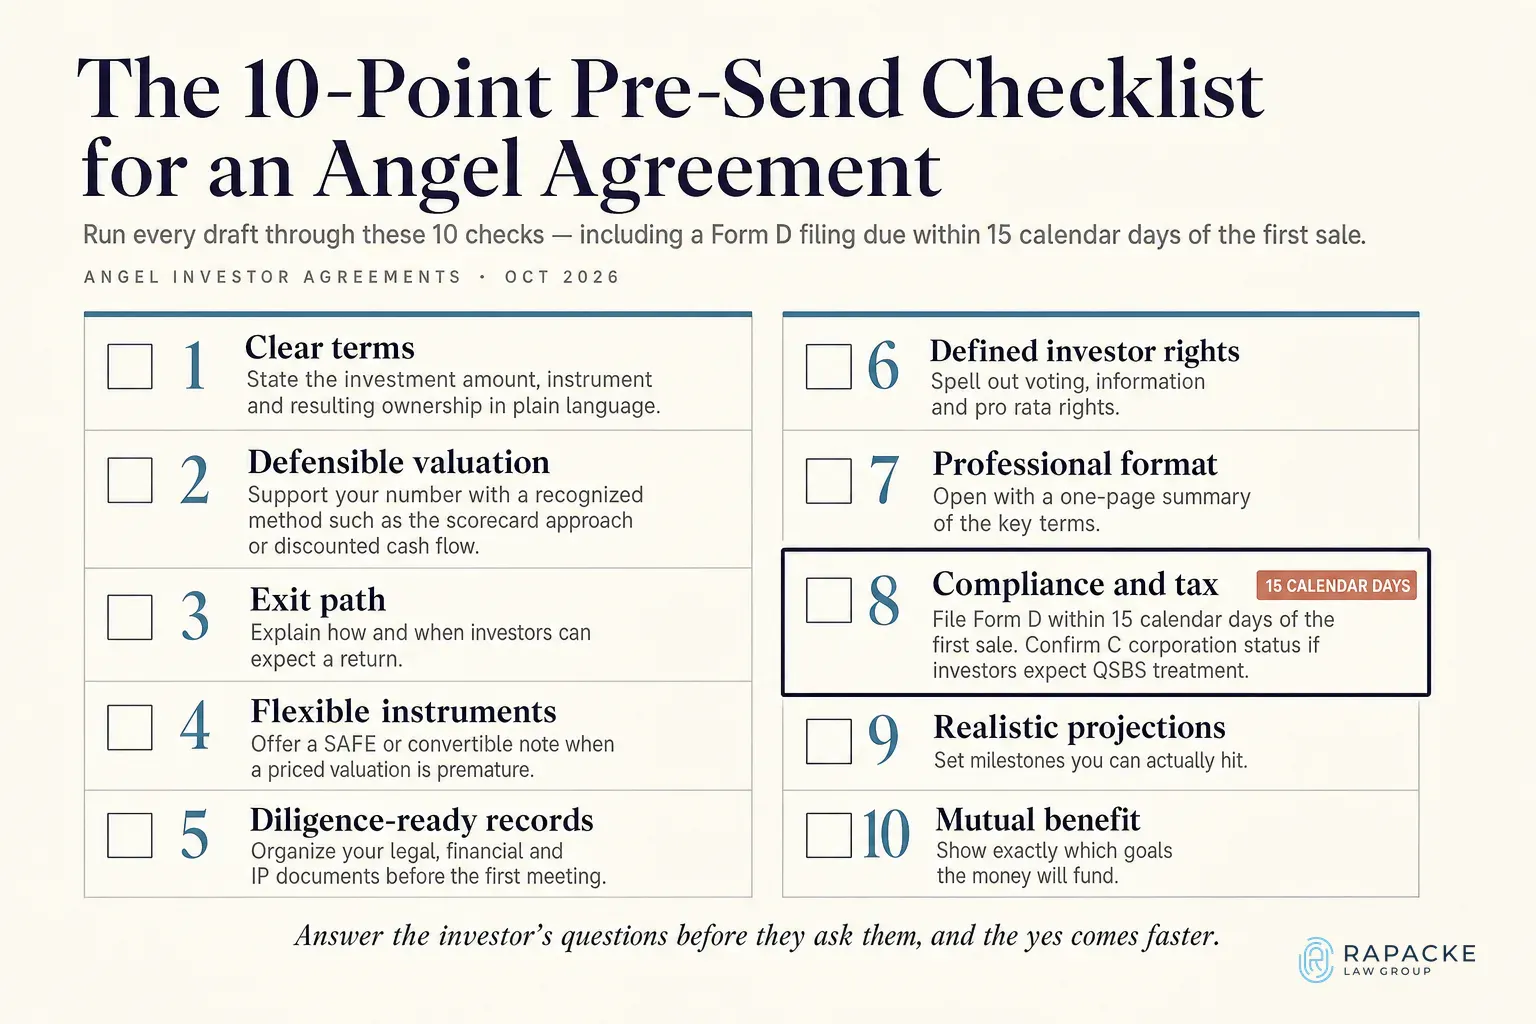
Investors say yes faster when your agreement answers their questions before they ask them. Run every draft through this checklist before it goes out:
Legal due diligence is where investors confirm two things. Your company can legally sell the securities, and it actually owns what investors are paying for. Most issues they uncover are fixable if you find them first.
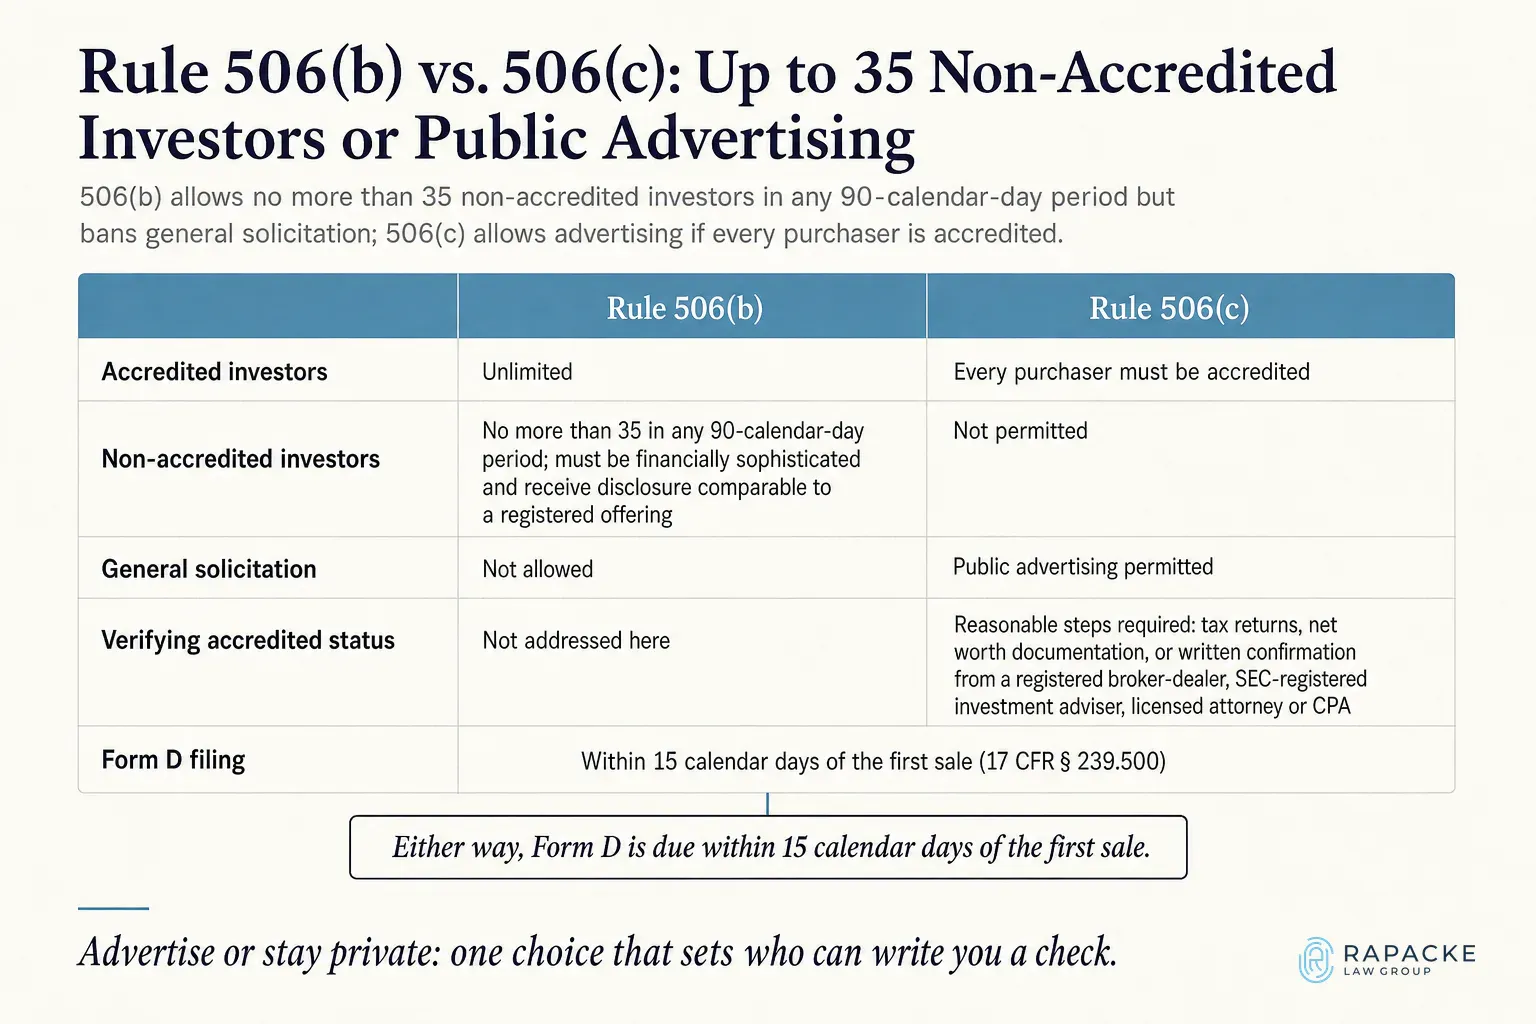
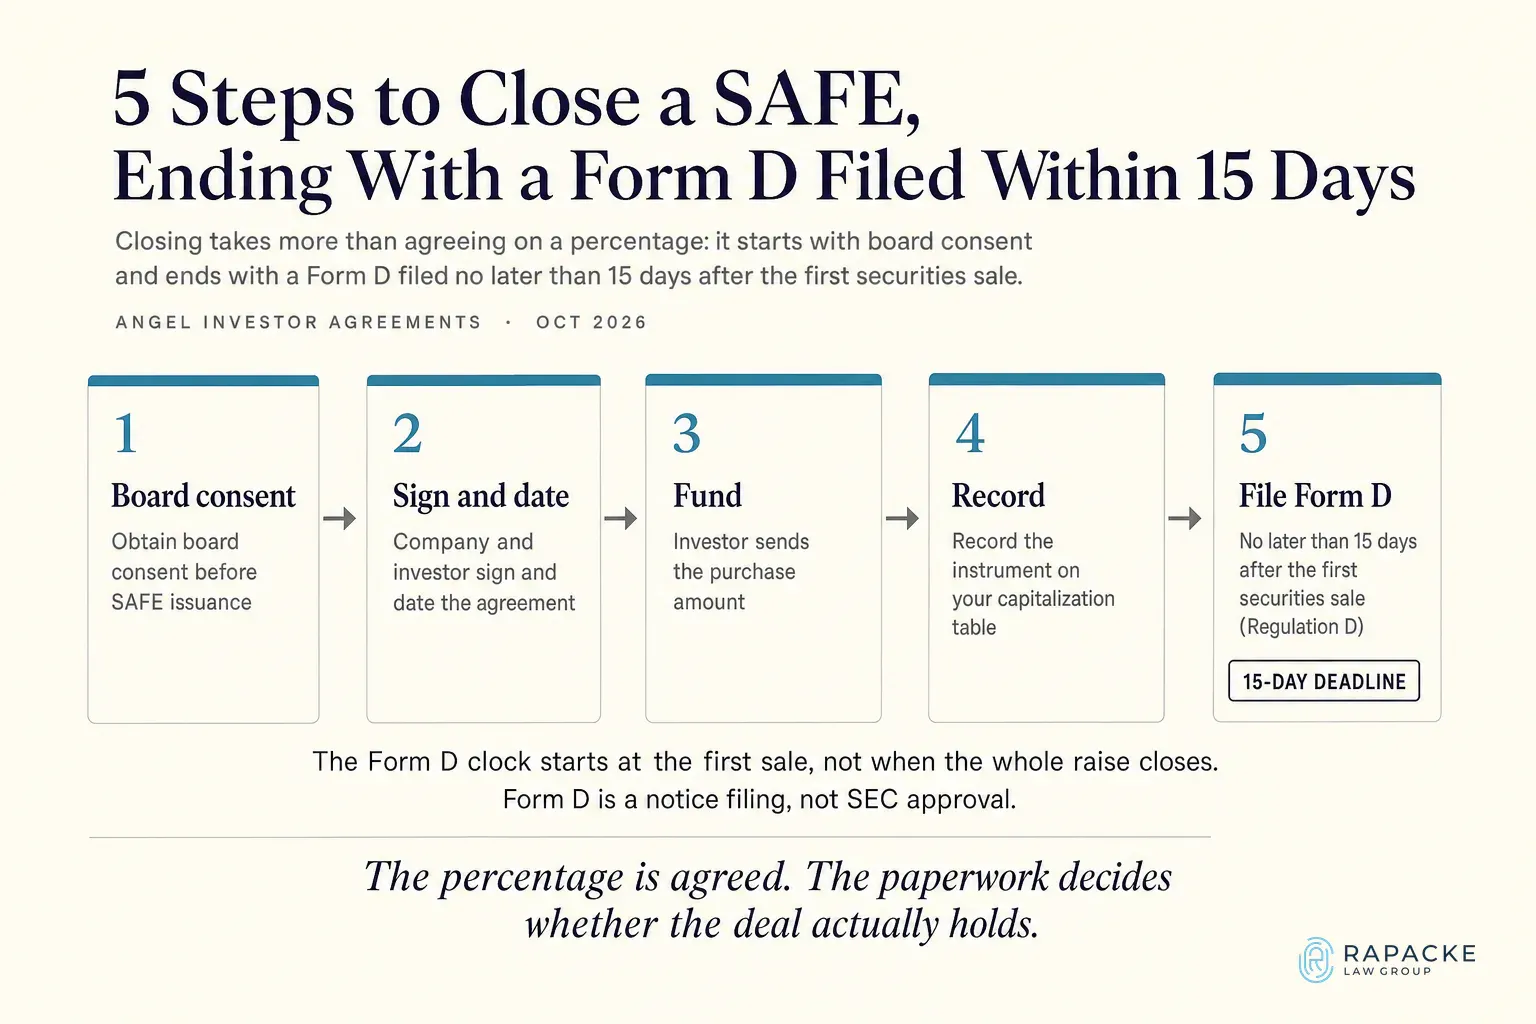
Bring in a lawyer after the term sheet is signed and before you sign the definitive documents, because that is when securities compliance, IP ownership and tax structure all get tested. Angel investors back founders they trust. A legal gap surfaced during due diligence breaks that trust fast. Start with securities compliance. Under the SEC's Rule 506(b), you can raise an unlimited amount from unlimited accredited investors but no more than 35 non-accredited investors in any 90-calendar-day period. You cannot use general solicitation, and any non-accredited investor must be financially sophisticated and receive disclosure comparable to a registered offering. Rule 506(c) lets you publicly advertise the raise, but every purchaser must be accredited and you must take reasonable steps to verify that status, according to the SEC. The SEC's Rule 506(c) guidance lists accepted verification methods, such as reviewing tax returns, checking net worth documentation, or obtaining written confirmation from a registered broker-dealer, SEC-registered investment adviser, licensed attorney or CPA. Either way, you must file Form D within 15 calendar days of the first sale, a deadline set by 17 CFR § 239.500.
Signed invention assignment agreements from every founder, employee and contractor close that gap. For SaaS and AI startups, investors also look at whether core code and models are protected, whether through patent filings or documented trade secrets. Our guides on why patents are important to investors and intellectual property strategy for SaaS startups explain how that protection shapes valuation. If you share inventions with development partners before filing, a patent non-disclosure agreement helps keep the details confidential. A clean cap table matters just as much. Y Combinator's SAFE guide calls for board consent before issuance and for recording each instrument on your cap table. Some investors also request a legal opinion confirming the stock issuance complies with law.
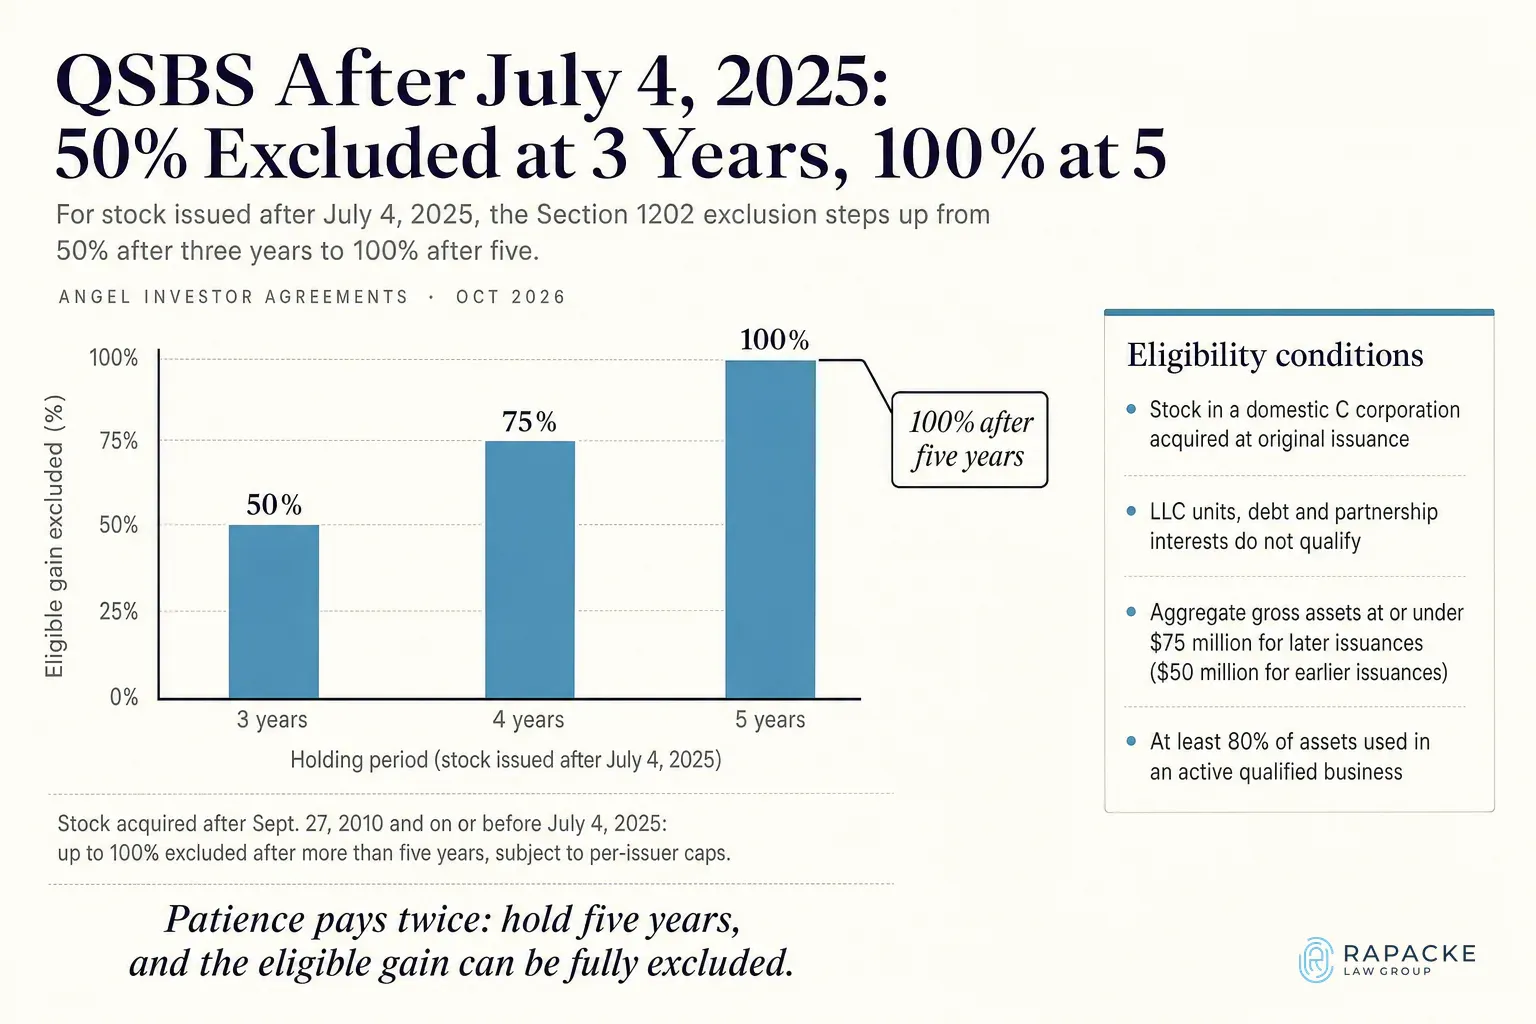
On taxes, investors generally pay capital gains tax on profitable exits. Losses from failed startups can offset other capital gains. Qualifying equity may also earn exclusions under Qualified Small Business Stock (QSBS) rules. Under Section 1202 of the Internal Revenue Code, QSBS must be stock in a domestic C corporation acquired at original issuance, so LLC units, debt and partnership interests do not qualify. For stock acquired after September 27, 2010 and on or before July 4, 2025, investors who hold more than five years can exclude up to 100% of eligible gain, subject to per-issuer caps. Stock issued after July 4, 2025 follows a tiered schedule, with 50% excluded after three years, 75% after four years and 100% after five. The company's aggregate gross assets must also stay at or under $50 million for earlier issuances or $75 million for later ones, and at least 80% of its assets must be used in an active qualified business. Rules and holding periods shift, so have your investors consult their tax advisors.
Before you sign, have an angel investor agreement lawyer review your documents. Book a Free IP Strategy Call with Rapacke Law Group.
Most bad angel deals come from founders signing terms they never modeled. Watch for these five:
Angel money has real downsides, including dilution, shared control, and exit pressure. The Angel Capital Association encourages founders to ask whether they will accept board decisions they may not always agree with and whether they have an exit plan investors can reach within five to seven years.
Angel investor agreements are the contracts that set the terms of an angel's investment in your startup. They define the instrument, the valuation or cap, investor rights and what each party receives at an exit.
A convertible note is short-term debt that converts into equity at a later priced round, usually at a discount or valuation cap. A note accrues interest and has a maturity date. A SAFE has neither, according to Y Combinator.
"Angel" describes who invests, which is typically an individual using personal money. "Seed" describes the financing stage, and angels commonly write checks in both pre-seed and seed rounds. The Angel Capital Association frames angel funding around early-stage companies that can reach an exit within several years, so one investor can be both an angel and a seed investor.
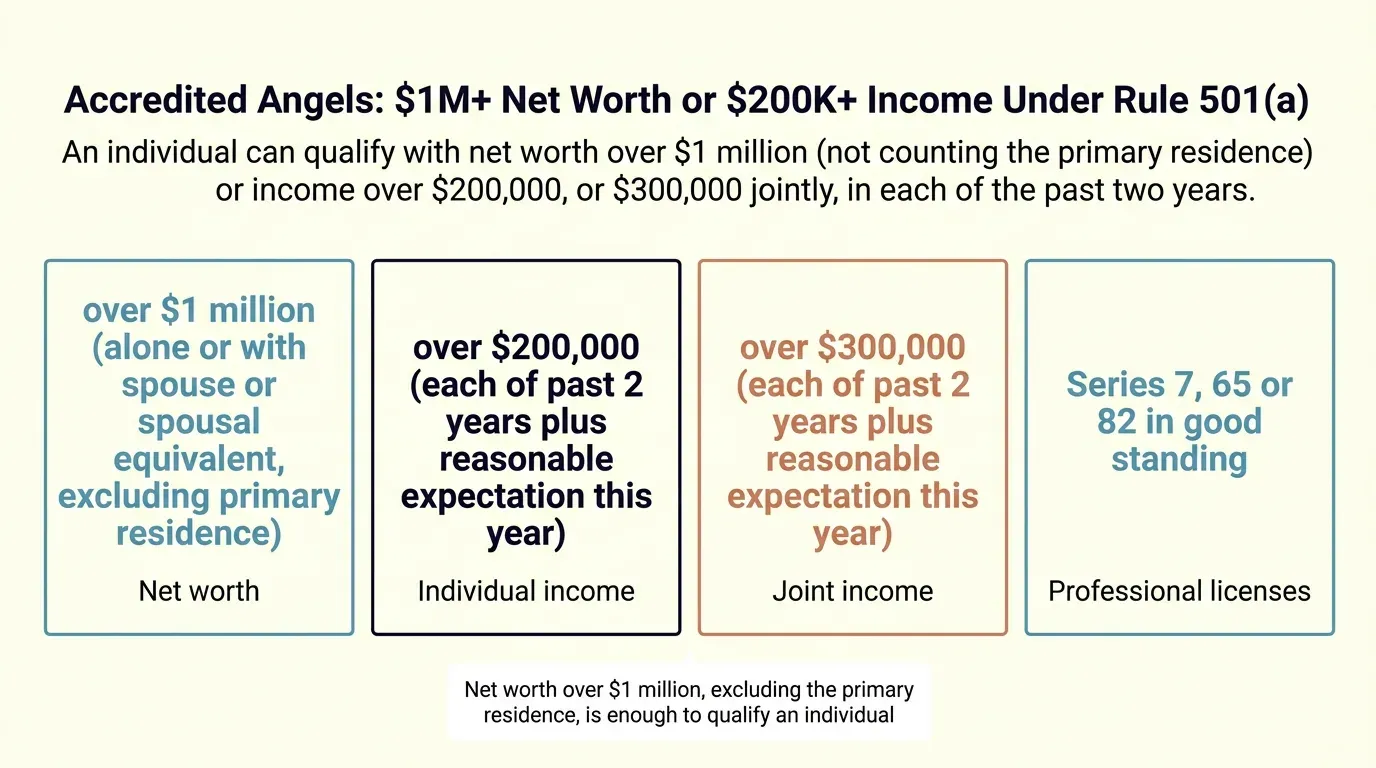
Many offerings require accredited status, which is defined under 17 CFR § 230.501(a). An individual qualifies with a net worth over $1 million, alone or with a spouse or spousal equivalent, excluding their primary residence. An individual also qualifies with income over $200,000, or $300,000 jointly, in each of the past two years and a reasonable expectation of the same this year. Holders of a Series 7, 65 or 82 license in good standing qualify as well. Rule 501(a) also includes other categories, such as directors and executive officers of the issuer, knowledgeable employees of private funds, and certain family clients.
Yes, if you want your terms to hold up under next-round due diligence. A startup attorney confirms that caps, liquidation preferences and side letters match your cap table. They also make sure you file Form D within 15 calendar days of the first sale in a Regulation D offering, as the SEC requires.
Angel investor agreements are the contracts that set the terms of an angel's investment in your startup. They define the instrument, the valuation or cap, investor rights and what each party receives at an exit.
A convertible note is short-term debt that converts into equity at a later priced round, usually at a discount or valuation cap. A note accrues interest and has a maturity date. A SAFE has neither, according to Y Combinator.
A term sheet locks in the economic and control terms before anyone pays for full drafting. It exposes deal-breakers early, when walking away is still cheap. Although most of it is non-binding, confidentiality and no-shop clauses usually bind you, so read them before you sign.
Acquisition is the most common exit for angel investors, while an IPO is rarer and far more complex. Angels can also sell shares in a secondary transaction or through a company buyback. The liquidation preference, drag-along and tag-along terms in your agreement decide how the proceeds are split.
Angels generally owe capital gains tax when they sell shares at a profit, and losses on failed startups can offset other capital gains. Stock in a qualifying C corporation may also be eligible for the QSBS exclusion under Section 1202, which can remove up to 100% of eligible gain after a five-year hold. Holding periods and thresholds changed for stock issued after July 4, 2025, so investors should confirm their position with a tax advisor.
Angel investors say yes to agreements that are easy to model and hard to poke holes in. That means clear economics,defined investor rights, clean Regulation D compliance and proof that your company owns the technology investors are paying for.
The bottom line: A weak IP position, such as unassigned code or no patent filings on your core software or AI, gives angels a reason to cut your valuation or walk away. A strong position, with signed assignments and filed patent applications, turns your technology into an asset investors can underwrite.
Diligence gaps tend to surface at the worst moment, usually after the term sheet is signed and the no-shop clock is running. A missing invention assignment or a late Form D filing can delay a close, force a renegotiation or follow you into your Series A data room. Fixing these issues before you pitch costs far less than fixing them under deadline.
Here is how to get ready:
Rapacke Law Group works on a fixed-fee model, so you know the cost before work starts and can budget legal spend alongside your raise instead of watching hourly bills climb during diligence. Founders who walk into a raise with protected IP and clean documents negotiate from strength, and that leverage shows up in their valuation, their terms and how quickly investors say yes.
To Your Success,
Andrew Rapacke
Managing Partner, Registered Patent Attorney
Rapacke Law Group
Connect with Andrew on LinkedIn, or follow @rapackelaw on Twitter/X and Instagram.
[RLG]Free strategy call
Talk it through with a registered patent attorney.
[01]Keep reading
Learn how to draft a startup advisor agreement with the right equity, vesting, and IP terms. Use FAST benchmarks and Carta data. Book a free IP strategy call.
Exit strategies for angel investors hinge on one factor most overlook: intellectual property. In 2024, U.S. venture-backed companies generated 1,259 exit events worth…
In a 2024 analysis of hundreds of startup outcomes, researchers found something striking: having any patents raised the probability of a successful exit by a measurable…
The #1 top reviewed IP law firm.* Talk to a registered patent attorney, free.
*#1 top reviewed means the most public client reviews on Google, Trustpilot and Avvo of any US patent or trademark firm.